STL decomposition
A monthly industrial turnover series split into trend, seasonal and remainder components in stacked panels.
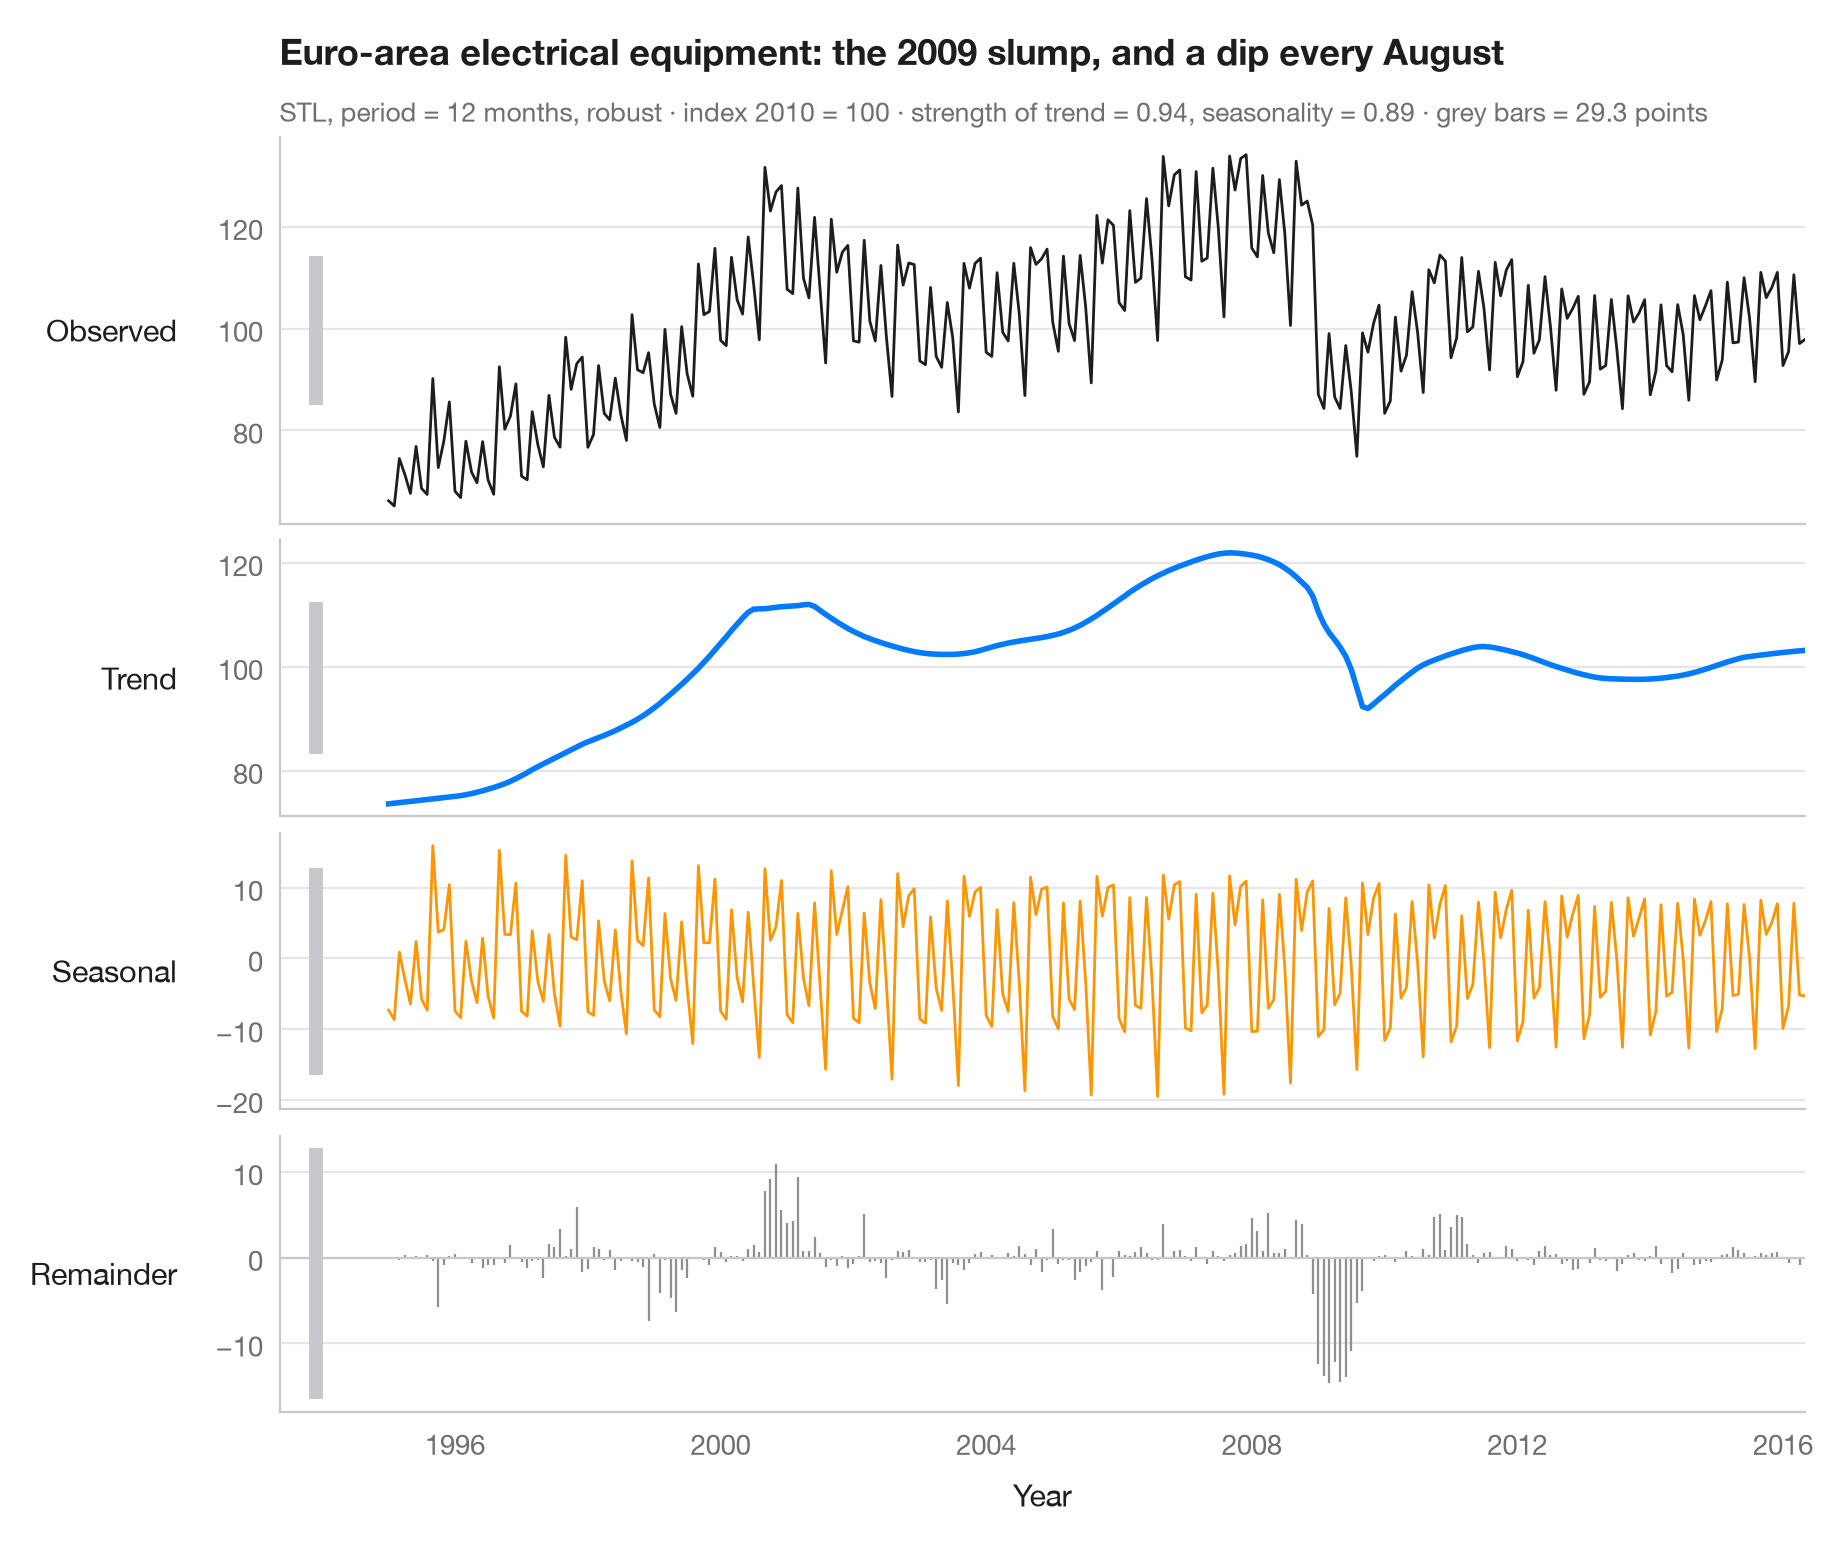
STL (Seasonal–Trend decomposition using Loess) writes a series as observed = trend + seasonal + remainder. Each panel shares the time axis but has its own vertical scale, so the grey bar on the left of every panel — all of the same length in data units — shows how large each component really is: a short bar means a component that dominates, a long one a component that is small.
Data are Eurostat's monthly turnover index for the manufacture of electrical
equipment in the euro area (2010 = 100), January 1995 to May 2016, working-day
adjusted but not seasonally adjusted — 257 months bundled with
statsmodels (statsmodels.datasets.elec_equip). The trend shows the
2008–09 collapse in industrial activity; the seasonal component shows the
August shutdown and the end-of-quarter peaks. The decomposition uses
statsmodels.tsa.seasonal.STL with a 12-month period and robust fitting; the
subtitle gives the strength of trend and seasonality as defined by Wang,
Smith & Hyndman (2006).
import matplotlib.pyplot as plt
import numpy as np
from statsmodels.datasets import elec_equip
from statsmodels.tsa.seasonal import STL

# Data: euro-area turnover index, electrical equipment manufacturing (2010 = 100), monthly
turnover = elec_equip.load().data.iloc[:, 0]

res = STL(turnover, period=12, robust=True).fit()
parts = {"Observed": turnover, "Trend": res.trend, "Seasonal": res.seasonal, "Remainder": res.resid}
colors = ["#1D1D1F", "#007AFF", "#FF9500", "#8E8E93"]

# Strength of trend and seasonality (0 = none, 1 = all the variation)
f_trend = max(0, 1 - res.resid.var() / (res.trend + res.resid).var())
f_seas = max(0, 1 - res.resid.var() / (res.seasonal + res.resid).var())

fig, axes = plt.subplots(4, 1, figsize=(9, 7.5), sharex=True,
                         gridspec_kw=dict(height_ratios=[1.4, 1, 1, 1]))
bar = 2 * res.resid.abs().max()  # common scale bar, in index points
x0 = turnover.index[0] - np.timedelta64(400, "D")

for ax, (name, s), c in zip(axes, parts.items(), colors):
    if name == "Remainder":
        ax.vlines(s.index, 0, s, color=c, lw=0.8)
        ax.axhline(0, color="#C7C7CC", lw=0.8)
    else:
        ax.plot(s.index, s, color=c, lw=2 if name == "Trend" else 1)
    ax.set_ylabel(name, rotation=0, ha="right", va="center", labelpad=14)
    # Scale bar: same height in index points in every panel
    mid = (s.max() + s.min()) / 2
    ax.plot([x0, x0], [mid - bar / 2, mid + bar / 2], color="#C7C7CC", lw=5, solid_capstyle="butt",
            clip_on=False)

axes[-1].set_xlabel("Year")
fig.align_ylabels(axes)
axes[0].set_xlim(x0 - np.timedelta64(200, "D"), turnover.index[-1])
slump = res.trend.diff(12).idxmin().year                                  # steepest yearly fall
low = res.seasonal.groupby(res.seasonal.index.month_name()).mean().idxmin()  # weakest month
axes[0].set_title(f"Euro-area electrical equipment: the {slump} slump, and a dip every {low}", pad=26)
axes[0].text(0, 1.04, f"STL, period = 12 months, robust · index 2010 = 100 · strength of trend = "
             f"{f_trend:.2f}, seasonality = {f_seas:.2f} · grey bars = {bar:.1f} points",
             transform=axes[0].transAxes, fontsize=9.5, color="#6E6E73")
plt.show()
Figures use the optional PyStatlas style: add plt.style.use("pystatlas.mplstyle") to match the look exactly.
Data source
- Euro-area electrical-equipment turnover, monthly, 1995–2016. Eurostat. Euro area (18, fixed composition) total turnover index, manufacture of electrical equipment (NACE Rev. 2), working-day adjusted, not seasonally adjusted. https://ec.europa.eu/eurostat
Distributed with statsmodels (statsmodels.datasets.elec_equip); public domain.
The examples illustrate statistical methods. Their titles describe what each figure shows in these particular data — often a small, dated or partial sample — not the author's position on the substantive question. For interpretation, context and data quality, rely on the original sources cited here.
How to cite
PyStatlas is created and maintained by Thierry Warin. If it helped your work, please cite it.
Warin, T. (2026). STL decomposition. In PyStatlas: A Python Gallery of Statistical Graphics for the Social Sciences. https://warint.github.io/pystatlas/time-series/stl-decomposition/
@misc{warin2026statlas,
  author       = {Warin, Thierry},
  title        = {PyStatlas: A Python Gallery of Statistical Graphics for the Social Sciences},
  year         = {2026},
  howpublished = {\url{https://warint.github.io/pystatlas/}},
  note         = {Source code: https://github.com/warint/pystatlas}
}More in Time series
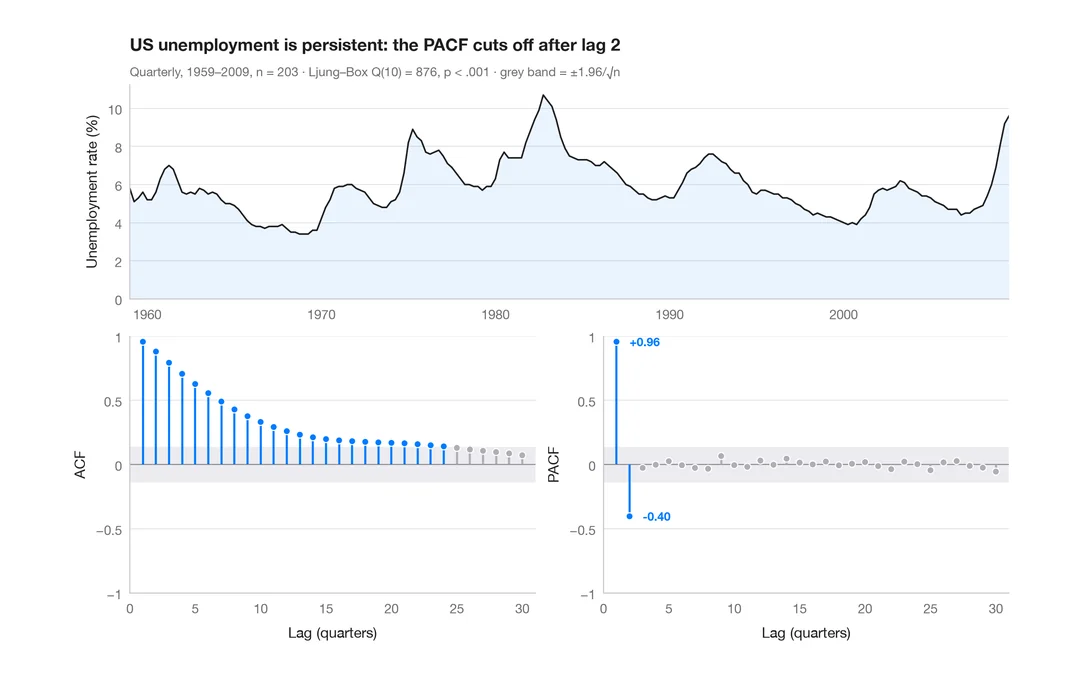
ACF and PACF
Autocorrelation and partial autocorrelation of US quarterly unemployment, as lollipops with 95% significance bands.
forecast::ggtsdisplay()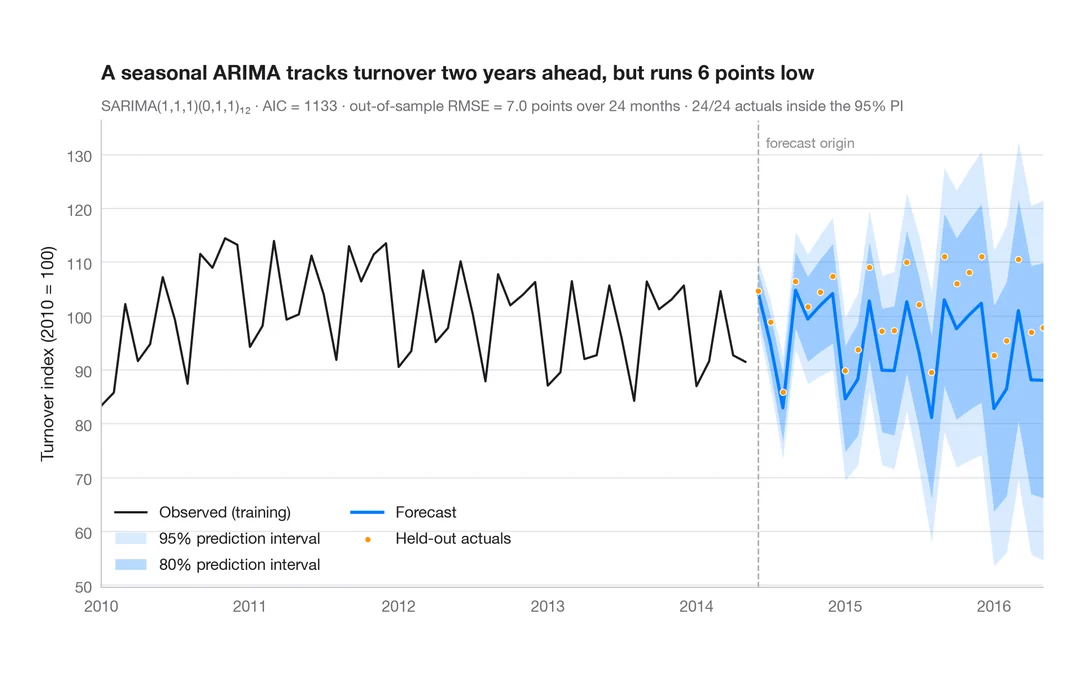
SARIMA forecast
Seasonal ARIMA forecast of industrial turnover with 80% and 95% prediction intervals against held-out data.
forecast::autoplot(forecast())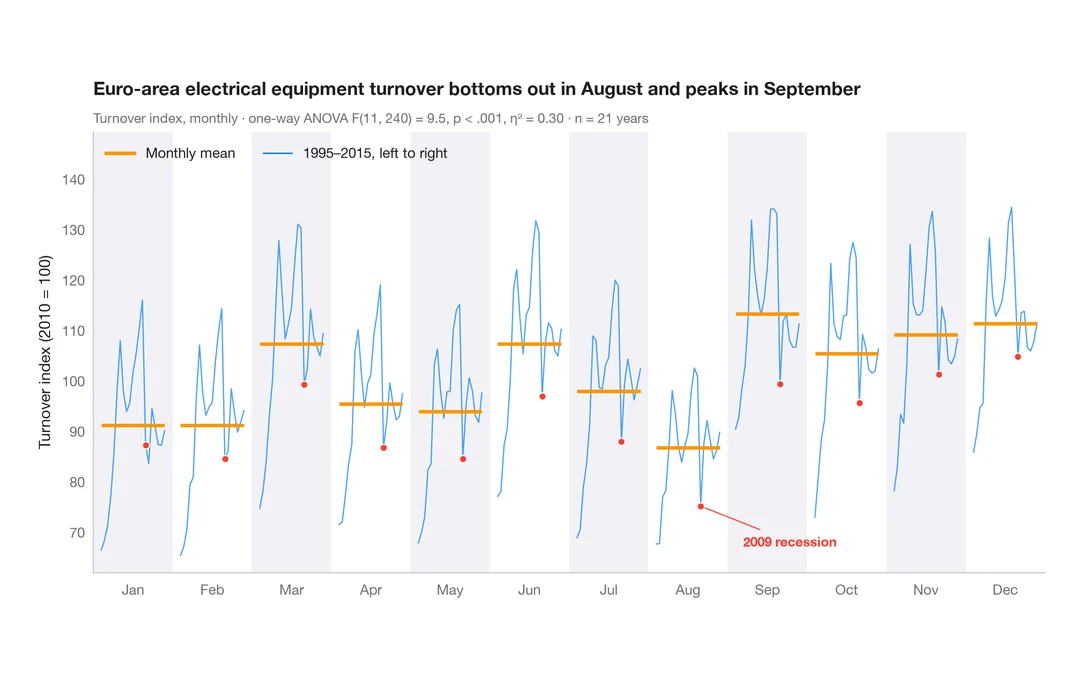
Seasonal subseries plot
Each calendar month's industrial turnover across the years, with the monthly mean as a reference.
feasts::gg_subseries()